

The ink on this one is barely dry and the real work is only just beginning. Netflix has said it plans to buy Warner Bros. Discovery’s studio and Max / HBO business for something in the neighborhood of $80 billion, with the old cable networks spun out into a separate company called Discovery Global and a long, noisy regulatory process ahead. If it closes, Netflix will be the fourth corporate owner of Warner in roughly fifteen years, after Time Warner, AT&T, and Warner Bros. Discovery. It is the kind of deal that sends everyone to the same checklist: price, breakup fee, who overpaid, who gets fired.
All of that matters but none of it is the real story. Open your TV tonight and imagine the Netflix app looks the same. Same red N. Same rows. Same frictionless scroll. Only now, behind that icon, sit Netflix originals, HBO, Warner Bros films, DC, Harry Potter, Looney Tunes, Adult Swim, and a century of studio muscle that used to belong to somebody else.
That is the actual headline under the headlines. Netflix is not just buying a studio. It is buying the pipeline that feeds HBO, folding Max into its own service, and leaving the old cable channels to live or die somewhere else. It is taking on a long review and a multibillion dollar breakup fee because the prize is not one more logo. The prize is to hard-wire itself in as the default front door for premium TV and film.

Amanda Lotz has been saying for years that the real shift was never broadcast to streaming. It was channels to portals. Channels were fixed schedules inside a bundle you rented by the month. Portals are software. They decide which rows appear, which tiles you see, what the default plan costs, and which account sits behind the remote. HBO Max used to be one of those portals. If this closes, HBO turns into a branded room inside Netflix’s house.
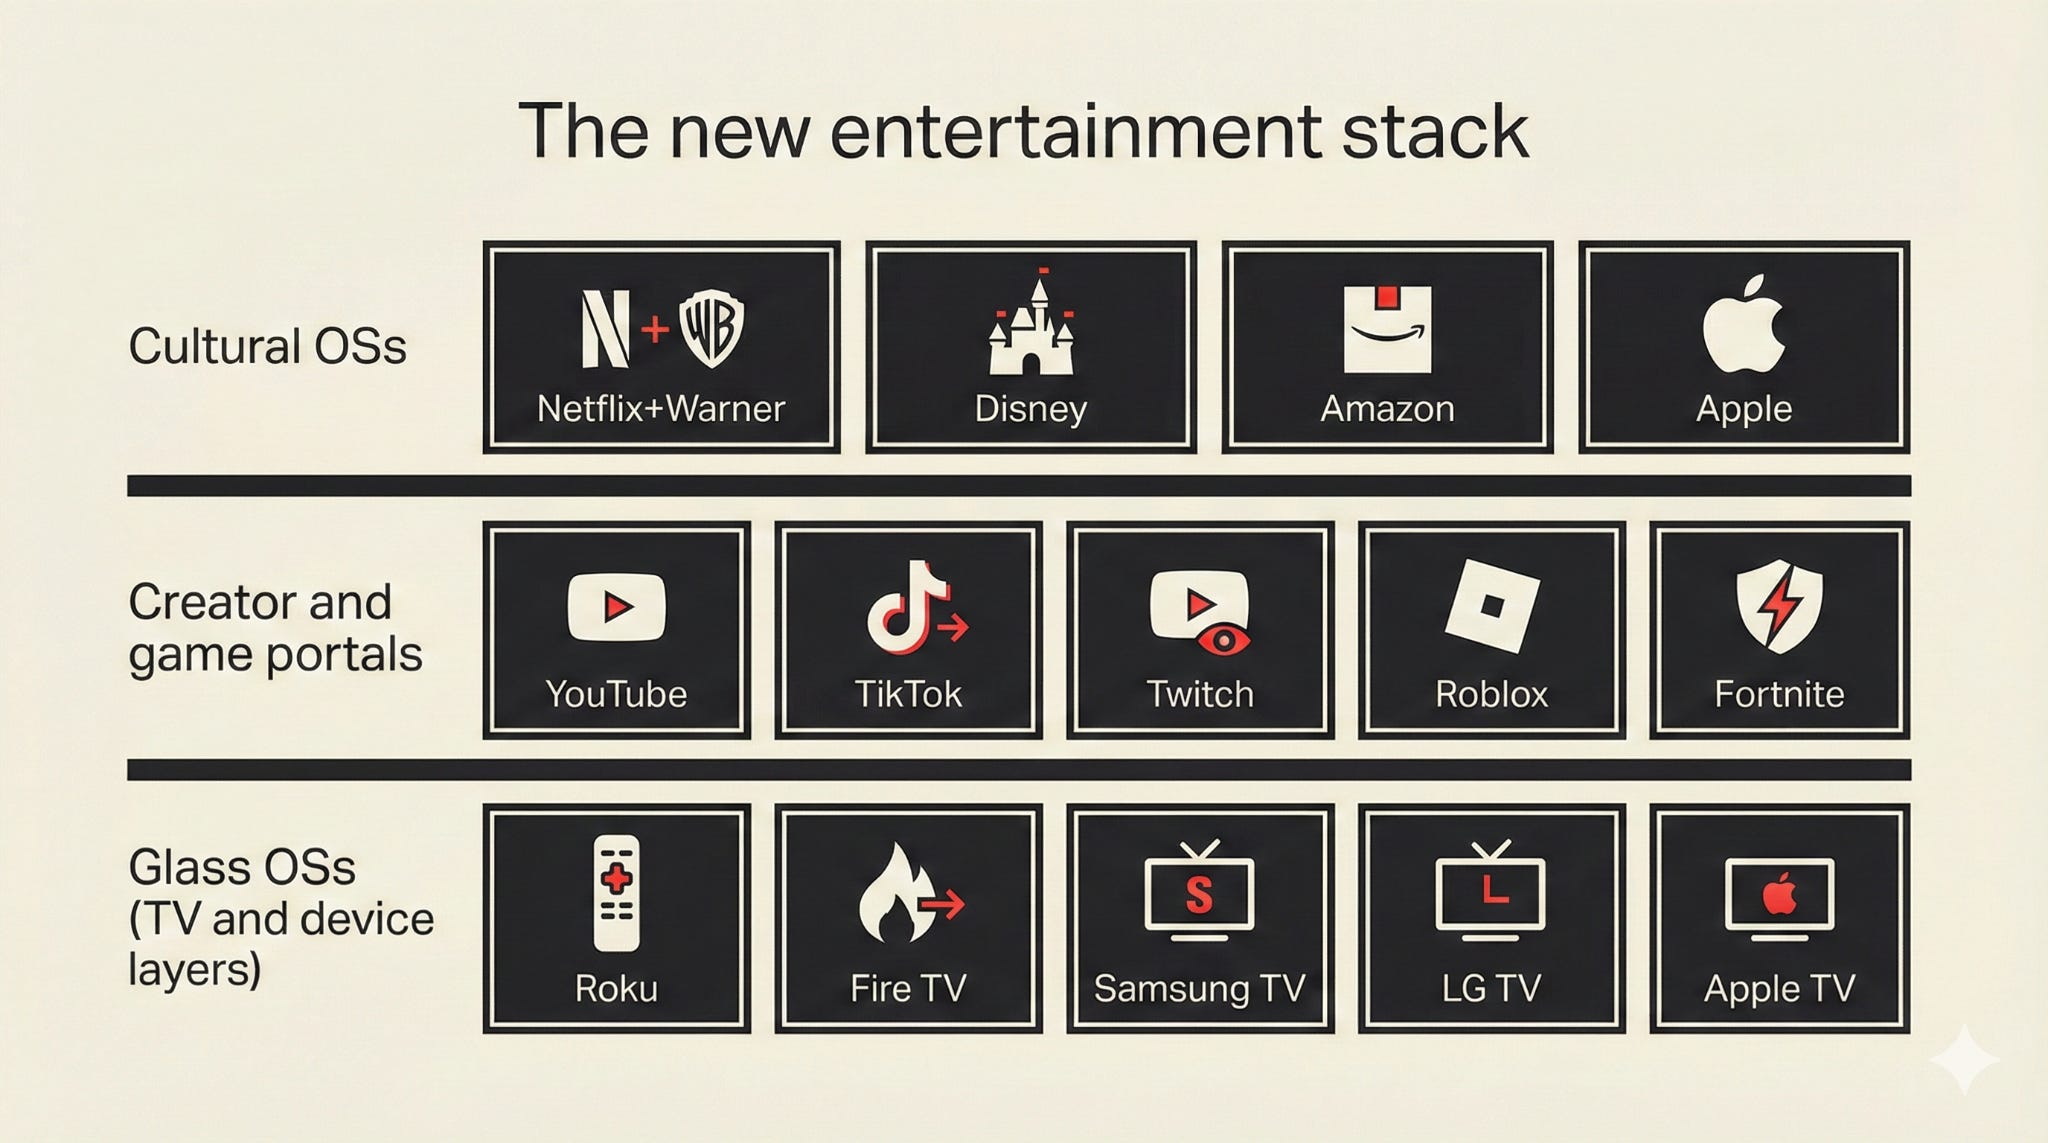
That is where the phrase “operating systems for culture” comes in. I am using the operating system metaphor on purpose: not as a software metaphor for its own sake, but as a way to talk about the layer that sets defaults, permissions, and priorities for everything that runs on top. What matters now is not just who owns which shows. It is who owns the operating systems that sit between those shows and your attention. A cultural OS is a portal plus a library plus an ad rail plus an identity graph. It is the combination of front door, catalog, targeting, and data that quietly decides what gets made, what gets surfaced, and who gets paid.
Over the last decade we let a handful of these OSs grow in parallel. Netflix in premium streaming. Disney in worlds and sports. Amazon in commerce. Apple in devices. Comcast and Paramount are trying to drag the old bundle forward. YouTube, TikTok, Twitch, and Roblox building their own universes on a different axis entirely. The Netflix and Warner deal is the moment those worlds stop feeling like a loose collection of services and start to look like a small set of operating systems we will all be living inside.
If you are a free reader, this is the point where you can safely bail out with the headline version: the portal is buying the studio, and the front doors are starting to harden.
If you are a paid subscriber, the rest of this piece is where we zoom in. What a combined Netflix and Warner actually looks like as an OS. How Disney, Amazon, Apple, Comcast, Paramount, YouTube, and TikTok line up around it. Where the ad rails, the workers, and the AI tools fit into that stack. And what you should be watching over the next 12 to 18 months if your job or your business depends on how this story plays out.
Netflix + Warner: the default premium OS
If you strip away the drama and look at the plumbing, four pieces snap together.
First, the portal. Netflix already sits on hundreds of millions of subscriptions, a working ad tier, and a home screen that has become the default start button for premium TV in a lot of households. That front door is now the entry point to far more than the Netflix slate.
Second, the pipeline. Max and HBO stop being a parallel service and become a branded feed inside the Netflix app. The same account that auto plays your Netflix crime doc now carries the next season of The Last of Us. The HBO commissioning culture does not vanish overnight, but its output is routed through someone else’s operating system.
Third, the studio. Warner Bros is not just logos on the front of buildings. It is a global production machine and a century of catalog. Films, series, animation, DC, adult animation, reality formats, kids. All of that now sits behind the same login that used to be “just” a streamer.
Fourth, the ad rail. Netflix has spent the last two years standing up a premium ad product and a household graph that knows how, when, and where people watch. Fold in HBO and Warner inventory and suddenly that ad rail sells itself as the place to reach audiences around both the most watched global series and some of the most respected brands in television.
From the viewer’s side, this does not present as a corporate diagram. It presents as one icon on the home screen. You click Netflix and walk through a house with more rooms. HBO is no longer a separate address. It is a wing. Warner is not a separate landlord. It is a set of doors at the end of the same hallway. The recommendation system is unified. The billing relationship is unified. The data exhaust is unified.
In Lotz language, a dominant portal has swallowed a rival portal and turned it into interior decor.
Who this is good for
You can tell three different truths here without pretending they cancel each other out.
For capital, this is probably the best exit Warner was going to get. Margins have collapsed from the cable era to the streaming era, and Warner has already burned through three corporate parents trying to rebuild around that reality. Selling into the one company that has actually proved it can run a global DTC machine is a rational move. You get a premium for assets the market had started to price as stuck, and you remove a complex balance sheet from a very unforgiving environment.
For workers, it is another round of turbulence on top of a decade of mergers and “transformations.” Any buyer in this price range was always going to promise “synergies,” and every prior deal has translated those synergies into layoffs, slate cuts, vendor consolidation, and more pressure on the middle of the market. The difference here is that one of the last big studio employers is now fusing with the biggest premium portal. Fewer independent portals means fewer distinct commissioning cultures and less leverage when you are trying to sell the next show, get the next season, or keep your crew intact.
For the system, this is the point where the layers fuse. The same company now controls a leading premium portal, one of the last major studio engines, a huge ad rail, and the identity graph underneath it. HBO could disappear as an independent portal and become a room. Warner disappears as a separate seller and becomes a set of internal relationships. That is not the end of competition in television. It is the beginning of a different kind of leverage.
Wu and Lotz at the same table
If you have read Tim Wu, the shape is familiar. He writes about communication industries sloshing between open and closed. Chaotic periods of experimentation and entry give way to order and bottlenecks. A handful of firms get control of the key chokepoints, then everyone spends a decade or two arguing about how much is too much.
On that curve, the Netflix and Warner deal looks like a bottleneck forming at the distribution layer. The messy multi service era of “everyone launches an app” is ending. One of the main pipes is welding itself directly to one of the main factories.
Lotz gives you the other half of the language. The choke point in this phase is not a channel or a piece of hardware. It is the portal. The front door on the glass. When HBO Max existed beside Netflix, you were still making a choice between two portals that framed similar kinds of work in different ways. HBO had its own interface, its own defaults, its own plan structure. Once it lives inside Netflix, your first decision is binary. Netflix or something else. HBO exists only if you choose Netflix.
That shift ripples all the way back into how projects are judged. Greenlights might no longer just be “is this a good Warner movie” or “is this a good HBO series.” They become “does this make the Netflix portal stronger.” Windowing equally becomes a lever inside the OS. Maybe a film gets a theatrical run because that drives the right kind of buzz before it lands in the app. Maybe it goes straight to Netflix because the retention math wins. The cancellations that feel arbitrary from the outside are often the ones that do not fit the operating logic of the portal, even if they work fine as one season of television.
So you have Wu’s bottleneck, where power clusters at a small number of chokepoints, and Lotz’s portal, where that power shows up on the home screen. The Netflix and Warner combination is what it looks like when those two ideas meet.
Three quick lenses: ads, labor, AI
I am going to come back to all three of these in more detail later, but they deserve at least a first pass now.
On the advertising side, Netflix and Warner together become one of the biggest premium CTV pools in existence. Netflix can now walk into the market and offer advertisers reach across its global slate and the HBO and Warner catalog in a single buy, with one household graph and one set of measurement tools behind it. That resets the story for Disney, Comcast, and YouTube about who really owns “premium video” for brand safe campaigns. It also raises the stakes in the quiet war over TV OS home screens and retail media networks, because the value of those surfaces goes up when one app carries that much inventory.
On the labor side, the word “synergy” is doing a lot of damage. We know what it has meant in every prior deal. Fewer overlapping departments. Fewer duplicative shows. Tighter vendor lists. More work for fewer teams under more pressure. The part that changes this time is the structural context. It is one thing to work for a studio that has to negotiate with multiple distributors and portals. It is another to work for an entity that is both your employer and the main gateway to the audience you want. That shapes everything from contract terms to day rates to how easy it is to walk away if you do not like the deal.
On AI and rights, a combined Netflix and Warner stack can credibly say that its internal tools are trained on content it owns or controls. Recommendation engines, dubbing, localization, synthetic extras, marketing cuts. All of this can run on a closed base of Warner and Netflix material and be sold as “fully licensed.” For creatives and guilds, that shifts the battle lines. You are no longer just negotiating clauses about reuse on one show. You are negotiating inside a vertically integrated system that can reuse performances, styles, and catalog across an entire operating system.
Each of these deserves its own deep dive. For now, the important point is that all three sit inside the OS frame. Ads are how the OS pays for itself. Labor is how the OS is staffed and constrained. AI and rights are how the OS automates and extends itself.
What the critics and the defenders are actually right about
The reaction so far has split into three camps.
On one side, you have the loud opposition. Regulators are already signaling “heavy skepticism.” Paramount’s lawyers have told Warner that a Netflix deal will “never close” and would entrench Netflix’s dominance in ways competition law should not allow. The Writers Guild, SAG-AFTRA, and the Producers Guild are warning about job losses, lower wages, worse conditions, less diverse output, and higher prices. Some of that is genuine fear. Some of it is tactical. All of it is pointed at the same anxiety of too much power in one place.
On another side, you have the clean market share argument that Tom Merritt laid out in his newsletter last Friday. If you zoom all the way out to total TV viewing, this is not the Death Star. It is roughly the sixth largest TV company buying the seventh largest, ending up just ahead of YouTube. Even in pure streaming share, YouTube remains bigger than a combined Netflix and Warner. On those scorecards, you can tell a straight faced story that streaming is still competitive, that Disney, Amazon, Apple, and YouTube are strong, and that this deal does not magically turn Netflix into a monopoly.
Both of those stories contain truth. Both also miss something important if you stop there. Broad share numbers are a useful antidote to the laziest “this is the end of competition” takes. They remind people that YouTube exists, that Disney has its own universe, that Amazon is not going away. Where they fall short is exactly where the union statements and Paramount’s warnings instinctively point. The worries are not really about whether other places to watch video exist. They are about one portal controlling a major studio, a premium global feed, and a large ad rail, and then using that stack to set the terms for everyone else.
Paramount is playing to its own interests. It has a direct interest in convincing Warner’s board that a Netflix deal will die in court so that its own offer looks cleaner. The guilds are doing what guilds should do, which is organize around the worst plausible version of the future so they have leverage now. And Tom is doing what good tech commentators should do, which is clean up the fuzzy antitrust rhetoric and ask whether the numbers justify the panic.
Underneath all of that, the structural worry is simpler. In the older channels world, Warner having a new owner was mostly about who collected the money and who made the calls in Burbank. In a portals world, Netflix buying Warner is about who owns the front door and the operating system behind it. If you think in channels and share charts, this looks manageable. If you think about portals and operating systems, it looks like a line being crossed.
The other operating systems for culture
So if this moves forward and Netflix and Warner are one operating system for culture they are far from the only one. Three other players sit very close to that same tier, but they are built on different foundations.
Disney: worlds and sports
Disney’s portals are Disney+ and Hulu. That is the front door. Behind it sit the “rooms” everyone can name by heart: Marvel, Star Wars, Pixar, Disney Animation, National Geographic, Hulu Originals, and ESPN.
What Disney sells is not a slate. It sells worlds. It sells the feeling that you live inside Marvel or Star Wars or the Disney canon across movies, series, parks, cruises, merch, and games. ESPN gives that a spine of live sports that trains people to come back on a schedule as well as a feed.
In Lotz terms, Disney has taken channel-era assets and rebuilt them as a brand-universe portal. ABC and ESPN are still channels in the old sense, but Disney+ and Hulu are where the company wants you to live. The cable bundle is becoming the marketing layer for the portal, not the other way around.
On the ad side, this looks like a coherent, brand-safe premium OS. Disney+ with ads, Hulu with ads, and ESPN inventory can be stitched together into one narrative for buyers who want reach, sports, and a logo their clients recognize. Whatever you think of the creative choices, structurally Disney is the “worlds and sports” operating system sitting next to Netflix’s premium scripted OS.
Amazon: commerce with a video layer
Amazon’s portal is Prime. Prime Video is one service behind that door.
From Amazon’s perspective, The Lord of the Rings, the NFL, reality formats, and licensed films are all tools to keep you inside the Prime operating system. The real product is the combination of fast shipping, streaming, audiobooks, grocery discounts, and a retail media network that sells ads against all of it.
Tentpole series and live sports are hooks. Watch Thursday Night Football, then buy the jersey, then have it delivered tomorrow. Watch a cooking show, then see the ingredient list inside the app. The entertainment layer, the retail media layer, and the logistics layer sit on the same stack.
As an ad OS, Amazon is the template for commerce-native video. It does not just sell impressions in front of a show. It sells access to what you put in your cart and how often you reorder. That is a different gravity than Netflix or Disney. It competes for the same ad budgets, but with a different promise.
Apple: the device-led meta-portal
On Apple’s side, the front door is still the Apple TV app, and the streaming service it fronts is now just called Apple TV. The app is a meta-portal. It pulls together Apple TV originals, third-party channels, store rentals, live sports, and whatever other services you thread through it.
Apple TV, the service, is one curated room inside that bigger frame. It does not need to be the place you watch everything. It needs to be the piece of the ecosystem that makes the hardware more valuable and keeps you inside Apple’s world alongside Music, Fitness, Arcade, News, and whatever spatial ends up becoming.
Sports is where you can really see the strategy harden slightly. Apple started with Major League Baseball. Then it cut a 10-year deal for MLS, and now it is dropping the separate Season Pass paywall so that, from 2026 on, every MLS match is included with an Apple TV subscription. Add the new exclusive U.S. rights for Formula 1 starting in 2026 and you have a pretty clear pattern: sports as a feature for the OS, not a standalone business. The point is to make “I watch soccer and F1 here” part of why you stay subscribed to Apple TV and keep an Apple device on your lap or in your hand.
The operating logic is simple. Content is a halo and a bundle sweetener, not the main revenue line. Apple’s money still comes from devices, services ARPU, and the cut it takes from the app rails everyone else needs to cross. Its foray into advertising is measured compared to Netflix, Disney, or Amazon. That restraint is partly brand, partly optionality. Apple can afford to treat ads and sports as levers it pulls to deepen the device ecosystem, not as the core of the business.
Put simply:
Netflix + Warner is the premium scripted OS.
Disney is the worlds and sports OS.
Amazon is the commerce OS.
Apple is the device ecosystem OS.
They all show up as tiles on the same home screen, but the systems underneath are wired for different outcomes.
The parallel portal universe
While Netflix, Disney, Amazon, and Apple fight over premium services, there is a whole other universe of portals that never cared about channels in the first place.
YouTube, TikTok, Twitch, Roblox, Fortnite, and the next thing that looks like them. These portals were built from day one around feeds, creators, and sessions. You open the app and you are dropped into a river of clips, streams, worlds, and recommendations tuned around who you are and what you do, not around a schedule.
For younger audiences, this is not the side dish, it is the main course. A huge share of global attention and ad spend lives here, especially under 25. These are the default places you go to watch someone break down a game, try a recipe, argue about a film, or build a world with friends. In Lotz terms, they were never channels. They have always been portals.
Why they matter in a Netflix + Warner moment
Structurally, these creator and game portals are the counterweight to the premium operating systems.
They keep talent from being fully absorbed. If you are a writer, comedian, gamer, or animator, you do not have to wait for a pitch meeting with Netflix or Disney. You can build your own audience on YouTube or TikTok, monetize through ads, sponsorships, fan support, and then decide whether you want to cross over to the premium OSs on your own terms.
They keep formats from freezing. Short, weird, interactive, live, chat driven, VTubers, collabs, UGC remixes. Most of the experimentation in how media actually feels to use is happening in these portals, not in carefully planned forty-seven-minute dramas on a Friday drop. They are already treating media as a programmable object, not a finished product. The thing I’ve been calling “media as programmable” is just daily reality here.
They also keep ad budgets from consolidating. Even if Netflix + Warner becomes the biggest premium inventory pool, any brand that wants to reach across younger demos or wants performance feedback in minutes, not quarters, still has to spend in the parallel universe. That limits how much any one premium OS can dictate terms.
So when Netflix moves to swallow Warner, you can take two views at the same time. At the top of the premium stack, we are watching portals harden into operating systems for culture. Underneath and around that stack, a different set of portals has already built its own operating systems for creators, formats, and attention. The fight is not just which app wins the living room. It is how much of your day ends up inside the premium OSs at all.
Everyone in the middle
All of this talk about operating systems can sound abstract until you remember who actually has to live inside them.
If you are making mid-budget work, the map just got smaller. There are fewer truly independent premium portals to sell into, and the ones that remain are under pressure to either chase global franchises or churn out cheap volume. The projects that land in the middle – smart, specific shows and films that are not IP farms and not bargain-bin fodder – have to fight harder to justify their slot. If they do not obviously strengthen an OS, they start to look like luxuries.
If you are running an indie streamer, a regional service, or a niche platform, survival now depends on having a very sharp reason to exist. Local rights, language, community, genre depth, a particular kind of relationship with your audience. Some of those services will find ways to work together, to share tech and rights and call it a co-op. Some will get bought and folded into the big OSs as “channels” or tiles. Some will just quietly wind down when the math stops working.
If you are a vendor, a post house, a systems integrator, a small tech company, you already feel the shift. More of your revenue is tied to a shrinking list of giant clients. Service-level agreements get tighter. More of the stack is automated or pushed into managed services. Integrations and certifications become another way to lock you to a particular portal’s way of doing things. You can still build a good business, but the margin for error is thinner, and the escape routes are fewer.
This is the part I want to come back to in more detail later. What does it mean to work for portals instead of channels, and how do you build a career or a company that does not get flattened in the process. For now, it is enough to say that when an operating system for culture hardens at the top of the stack, the first people who feel it are almost always the ones in the middle.
What to watch from here
From here, the story is mostly in the details as we watch and wait.
Start with Netflix itself. How it chooses to surface HBO and Warner inside the portal will tell you a lot. Do they keep clear rails and labels, or let everything blur into a single Netflix feed? Which brands get the hero slots, which ones get parked in carousels? The interface will quietly reveal who really counts inside the operating system.
Then pay attention to how “synergies” show up. Not just the headline layoffs, but the patterns underneath. Which slates get cut. Which vendors lose work. Where the mid-budget projects disappear first. If you want to see the shape of the new OS, follow the cancellations, not the key art.
The responses from Disney, Amazon, and Apple will sketch the rest of the map. Disney can bundle harder and lean deeper into worlds and sports. Amazon can wire more sports and tentpoles into retail media and Prime. Apple can keep stacking live rights on top of devices and services. Each move is a bet about which operating system story will actually carry the next decade of P&Ls.
Comcast and Paramount sit in a different kind of spotlight. They can double down on live and news and accept that they are channel-native. They can lean into being suppliers to the big portals. They can try one more time to reinvent themselves as peers. However they move will tell you how much real space is left outside the main OSs.
Underneath all of this, the money will keep drawing the outlines. New premium CTV packages built around Netflix and Warner. Shifts in spend away from cable, or away from YouTube and TikTok, or away from mid-tier streamers that cannot tell a clean story. Somewhere inside those budgets you will see which operating systems media buyers actually believe in.
Over that same stretch of time, pay attention to the AI and rights tells. You will start to see more “fully licensed” training claims in investor decks and onstage interviews. Synthetic tools will slip quietly into dubbing, background extras, localization, and personalization, framed as workflow upgrades rather than revolutions. The next rounds of guild negotiations will pull some of that into the open, and regulators will have to decide whether they care about the training stacks as much as the market share charts. Taken together, those signals will show how tightly this operating system is allowed to close around its own data.
We are past the part of the story where every company launches a service and calls it a strategy. We are in the part where a few portals harden into operating systems for culture. The headlines will keep coming, and the antitrust lawyers will keep arguing over charts and definitions, but our job is different. We have to keep educating ourselves about what those headlines really mean in terms of power, work, and access. We have to decide which operating systems we are willing to live inside, and how to keep room at the edges for everything that does not belong to them.
Cocktail Endnote: The Portal Old Fashioned
The Old Fashioned is one of the stalwarts of the cocktail world: spirit, sugar, bitters, ice. Simple, direct, hard to beat when you want the base spirit to do the talking. For this piece, I’m nudging that template a bit – adding a liqueur for more texture and flavor, and pulling back the syrup so the sweetness stays in check.
The ingredients:
2 oz rye
0.25 oz rich demerara syrup (2:1)
0.25 oz Benedictine
2 dashes Angostura
1 dash orange bitters
Stir with ice, strain over a big cube, orange peel on top.
The Benedictine is doing the same job I am hoping Netflix will do with Warner. It does not sit on top and shout. It slips into the base and makes everything a little deeper. You get honey, herbs, a bit of spice, and this slow, layered richness that shows up more with each sip.
It is a strong, slightly luxurious drink for a strong, very luxurious deal. Rich, a little bitter, and built to be taken in slowly while you think about who really owns the front door.
"We are past the part of the story where every company launches a service and calls it a strategy. We are in the part where a few portals harden into operating systems for culture."
The Portal Old Fashioned is the perfect companion for this piece.
Can you help me understanding the "training deck" a little better?